

Dimensioni e quota del mercato delle borse sportive negli Stati Uniti
Panoramica di mercato
| Periodo di studio | 2021 - 2031 |
|---|---|
| Anno base per la stima | 2025 |
| Periodo dei dati di previsione | 2026 - 2031 |
| Dimensione del mercato (2026) | USD 601.21 milioni |
| Dimensione del mercato (2031) | USD 984.65 milioni |
| Tasso di crescita (2026 - 2031) | 10.37% CAGR |
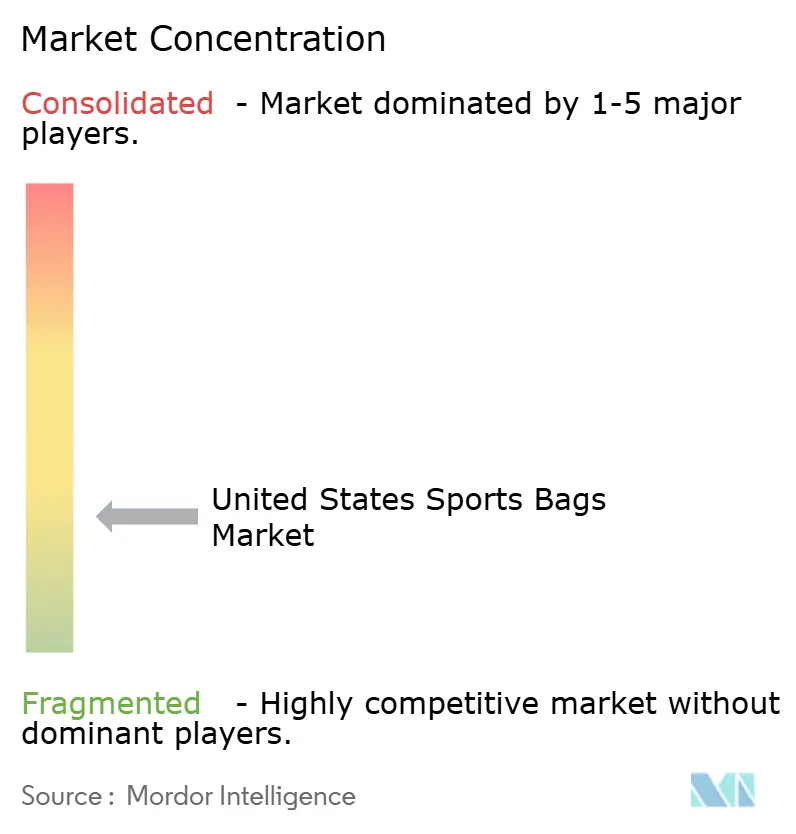
| Concentrazione del mercato | Basso |
Principali giocatori *Disclaimer: i giocatori principali sono ordinati senza un ordine particolare Immagine © Mordor Intelligence. Il riutilizzo richiede l'attribuzione secondo la licenza CC BY 4.0. | |
Analisi del mercato delle borse sportive negli Stati Uniti di Mordor Intelligence
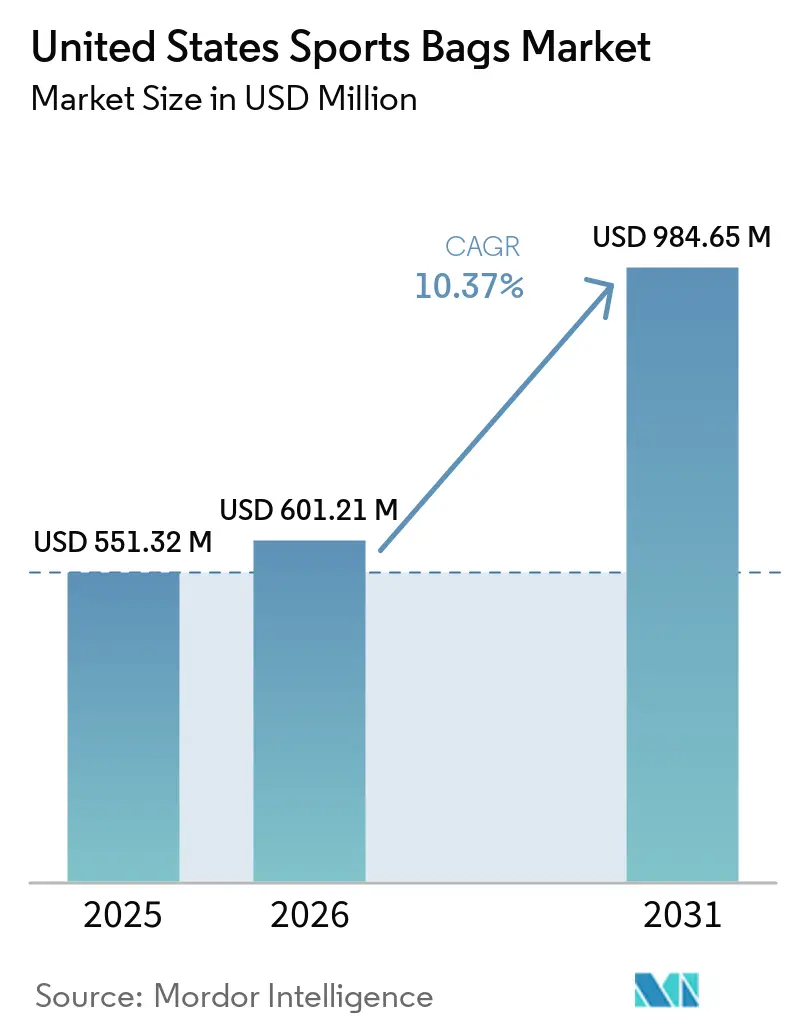
The United States sports bags market size is USD 601.21 million in 2026, up from USD 551.32 million in 2025, and is projected to reach USD 984.65 million by 2031, growing at a CAGR of 10.37% during 2026-2031. The United States sports bags market is supported by record participation in sports, fitness, and leisure activities, which broadens the base of consumers who need equipment-carrying products [1]Source: Sports & Fitness Industry Association, “Participation Hits New High, But Majority of Americans Not Yet Meeting Recommended Guidelines of 150 Minutes of Weekly Activity,” Sports & Fitness Industry Association, sfia.org. Youth programs create recurring demand because students need products that move equipment between school, practice, and competition. Product upgrades, including ergonomic straps and recycled materials, give brands reasons to compete on utility and durability rather than price alone. The United States sports bags market also faces pressure from counterfeits and multipurpose products, which can divert purchases from specialized designs. Fragmentation leaves room for established athletic brands, specialty suppliers, and retailers with differentiated assortments.
Punti chiave del rapporto
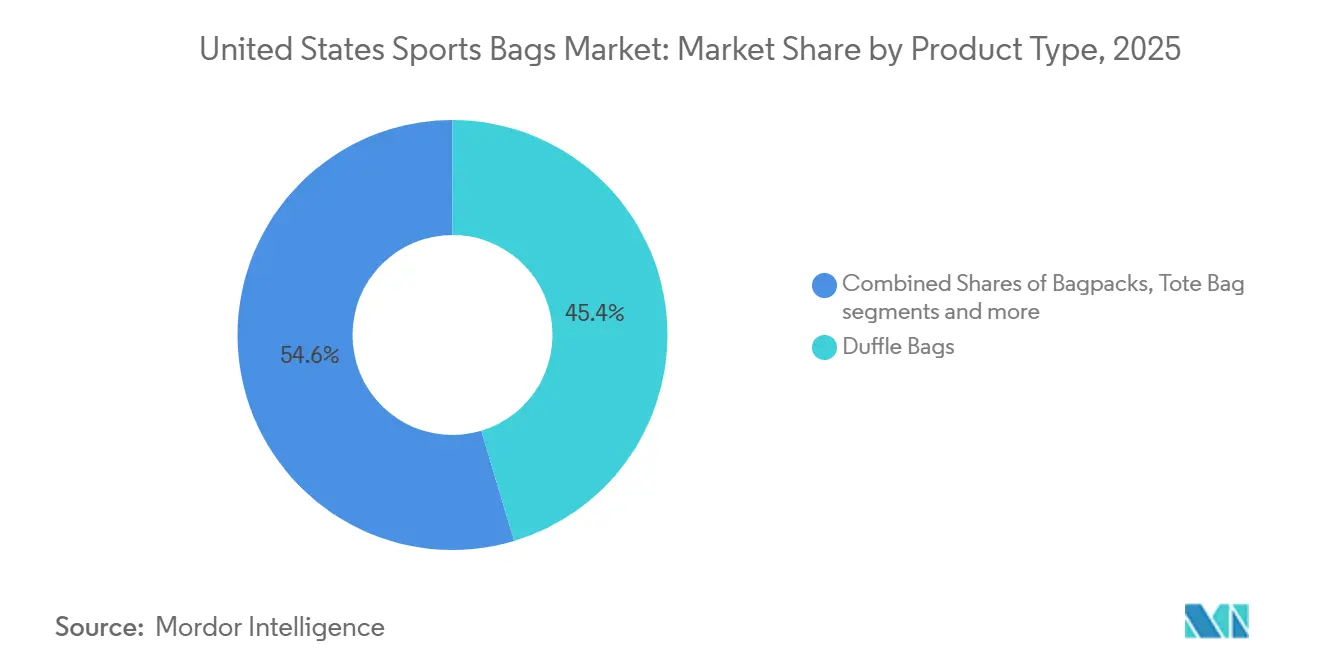
- By product type, Duffle Bags held 45.36% of United States sports bags market share in 2025, while Backpacks are projected to grow at an 11.68% CAGR through 2031.
- By sports type, Football held 35.42% of category sales in 2025, while Golf is projected to grow at a 12.21% CAGR through 2031.
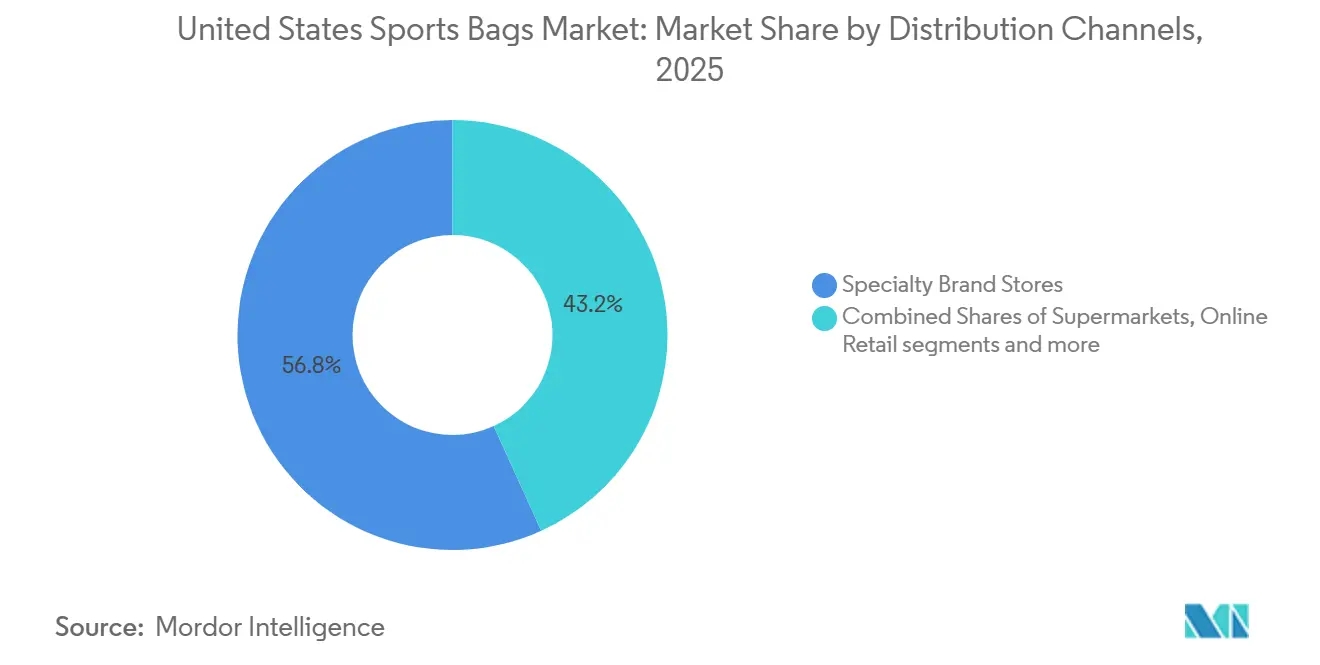
- By distribution channel, Specialty Stores held 56.78% of category sales in 2025, while Online Retail Channels are projected to grow at an 11.95% CAGR through 2031.
Nota: le dimensioni del mercato e le cifre previste in questo rapporto sono generate utilizzando il framework di stima proprietario di Mordor Intelligence, aggiornato con i dati e le informazioni più recenti disponibili a gennaio 2026.
Tendenze e approfondimenti sul mercato delle borse sportive negli Stati Uniti
Analisi dell'impatto dei conducenti
| Guidatore | (~) % Impatto sulle previsioni del CAGR | Rilevanza geografica | Cronologia dell'impatto |
|---|---|---|---|
| Aumentare la partecipazione ad attività sportive e di fitness | + 2.5% | National, with concentrated demand in Texas, Florida, and California | Medio termine (2-4 anni) |
| Growing popularity of athleisure and sports-inspired fashion | + 1.8% | National, strongest in New York, Los Angeles, and Chicago | Medio termine (2-4 anni) |
| Product innovation and advanced material development | + 1.5% | il | A lungo termine (≥ 4 anni) |
| Increasing demand for premium and branded sports bags | + 1.2% | National, with a premium skew in Northeast and Pacific Coast metros | A lungo termine (≥ 4 anni) |
| Growth of organized sports and youth athletic programs | + 1.0% | National, concentrated in Sun Belt and Mid-Atlantic states | Medio termine (2-4 anni) |
| Increasing demand for sustainable and customizable products | + 0.8% | National, with early adoption in California and the Pacific Northwest | A lungo termine (≥ 4 anni) |
| Fonte: Intelligenza di Mordor | |||
Increasing Participation in Sports and Fitness Activities
The United States sports bags market draws broad demand from participation across organized and individual activities. SFIA recorded 250 million Americans participating in at least 1 sport, fitness, or leisure activity in 2025, the highest reported total in its tracking history. The association also reported 158.8 million core participants, who take part in most occasions within their chosen activities, up 1.30% from the prior year. Team sports participation reached 92.3 million in 2025 and increased 7.60%, creating sustained requirements for products that carry uniforms, footwear, protective equipment, and hydration. The United States sports bags market benefits because team participants often replace or add equipment bags as their sport requirements change.
Growing Popularity of Athleisure and Sports-Inspired Fashion
The United States sports bags market benefits when products serve gym, commuting, travel, and everyday use. A sports bag can now be selected for its appearance, internal organization, and compatibility with work or school routines, in addition to its equipment capacity. This overlap supports demand for backpacks and duffles with a more refined exterior and flexible storage layout. It also reduces the difference between sport-specific products and lifestyle accessories for consumers who move between several settings during a day. Demand for sustainable and customizable products can reinforce this effect when brands offer visible recycled-content labeling or personalized features. California’s packaging law requires producers to meet source-reduction, recycling, and recycled-content requirements, which increases attention to material choices in consumer goods[2]Source: National Federation of State High School Associations, “High School Sports Participation Increases for 5th Consecutive Year,” National Federation of State High School Associations, nsga.org.
Product Innovation and Advanced Material Development
Product innovation gives suppliers a practical route to differentiate in the United States sports bags market. Under Armour introduced the No Weigh Backpack in 2025 with its patent-pending UA Suspension Strap System, designed to distribute load and reduce shoulder pressure. The range shows how ergonomic features can move from footwear and apparel into equipment-carrying products. Weather protection, compartment design, lighter materials, and modular storage can also make a product more useful across school, practice, and travel. These features may help brands defend higher prices when consumers can see a direct functional benefit. They also create a higher development standard for smaller suppliers that lack comparable design and testing resources.
Increasing Demand for Premium and Branded Sports Bags
Premium products influence the value mix of the United States sports bags market when consumers connect bag purchases with a wider equipment upgrade. Golf is relevant because total participation reached 48.1 million in 2025, including 29.1 million on-course golfers[3]Source: United States Golf Association, “Golf Participation Boomed in 2025, More Than 82 Million Rounds Posted Domestically,” United States Golf Association, usga.org. Those consumers often require specialized storage and protection for their equipment. Nike’s hard-shell suitcase collection, introduced in 2026 from USD 260, also places travel-oriented sports equipment within a higher-priced branded offering. Premium demand remains strongest where consumers can evaluate construction, fit, and sports-specific features before purchase. It does not remove the need for accessible entry-level products, especially for families managing several youth activities.
Analisi dell'impatto delle restrizioni
| moderazione | (~) % Impatto sulle previsioni del CAGR | Rilevanza geografica | Cronologia dell'impatto |
|---|---|---|---|
| Sensibilità al prezzo tra i consumatori | -1.5% | National, most acute in lower-income household brackets and rural markets | A breve termine (≤ 2 anni) |
| Availability of low-cost and counterfeit products | -1.2% | National, with high incidence in California, Texas, and Florida e-commerce markets | A breve termine (≤ 2 anni) |
| Cambiamento delle tendenze della moda e delle preferenze dei consumatori | -0.8% | Urban metros, where trend cycles move faster | Medio termine (2-4 anni) |
| Competition from multipurpose bags | -0.7% | il | Medio termine (2-4 anni) |
| Fonte: Intelligenza di Mordor | |||
Sensibilità al prezzo tra i consumatori
Price sensitivity remains a limit on the United States sports bags market, even as premium products gain visibility. Project Play reported that youth sports costs increased 46.00% from 2019 through 2025, placing pressure on household spending for equipment and related goods. SFIA reported that the inactive population reached 22.90% in the first half of 2025 amid market and economic uncertainty linked to tariffs. Consumers may defer a replacement bag if an existing product remains usable or if a general-purpose alternative is available. This pressure is strongest in the middle price range, where products may appear less affordable than entry-level formats but offer fewer distinctive features than premium alternatives. Suppliers can respond through entry collections, product bundles, and clear durability claims without weakening their main brand positioning.
Availability of Low-Cost and Counterfeit Products
Counterfeit goods create a direct restraint on the United States sports bags market by displacing legitimate branded purchases. Homeland Security Investigations and its partners seized USD 39.5 million in counterfeit sports merchandise across more than 214,000 items before Super Bowl LIX in February 2025. Operation Team Player has seized more than USD 455 million in counterfeit sports merchandise since 2013. Counterfeits can weaken perceived quality and confuse consumers who cannot verify the source of a product. Fast-moving fashion preferences can intensify this issue when consumers seek inexpensive versions of a new design. Multipurpose bags create a separate challenge because they can satisfy basic carrying needs without the cost of a specialized sports product.
Analisi del segmento
By Product Type: Backpacks Lead Growth While Duffle Bags Anchor Revenue
Duffle Bags held 45.36% of the United States sports bags market share in 2025, while Backpacks are projected to grow at an 11.68% CAGR through 2031. Duffles remain central to team logistics because their open construction and large internal volume can carry footwear, uniforms, protective equipment, and hydration products. Varsity programs, fitness clubs, and recreational leagues can specify this format when capacity and ease of access are more important than compact storage. Its role extends beyond formal teams because gym users and travelers also value a flexible bag that can hold bulky clothing and shoes. The United States sports bags market size for Duffle Bags therefore reflects routine institutional purchasing as well as individual travel and training needs.
Backpacks are gaining popularity because young athletes can use a single product for school materials, training apparel, personal technology, and smaller equipment items. Their hands-free format supports commuting between school, practice, and other daily activities. Under Armour’s 2025 No Weigh Backpack shows the focus on functional upgrades through a load-distribution strap system. Tote Bags appeal to casual gym users and lifestyle buyers who prioritize simple access and a less technical appearance. The Others category includes racket bags, wheeled bags, and hybrid formats that meet sport-specific carrying requirements not addressed by standard backpacks or duffles.
Nota: le quote di tutti i segmenti individuali sono disponibili al momento dell'acquisto del report
By Sports Type: Football Commands Market Scale While Golf Drives Premium Intensity
Football accounted for 35.42% of category sales in 2025, while Golf is forecast to expand at a 12.21% CAGR through 2031. Football’s position reflects its established school, college, and professional infrastructure across the country. NFHS recorded 8,415,684 high school sports participants in the 2025-26 school year, its fifth straight record. These programs create recurring requirements for products that carry cleats, pads, uniforms, and training items through long seasons. School athletic departments, clubs, and families may all purchase durable equipment bags to support these needs.
Golf’s faster growth is associated with rising participation and the use of specialized equipment. Total golf participation reached 48.1 million in 2025, including 29.1 million on-course golfers. USGA recorded 82 million scores posted in the United States in 2025, up 8.20% from the preceding year. Nine-hole scores reached nearly 15 million after rising 5.00%, which indicates continued participation among beginners and recreational players. Soccer, baseball, basketball, and snow and winter sports also maintain distinct bag needs related to equipment size, protection, and transport.
By Distribution Channel: Specialty Stores Defend Share While Online Retail Accelerates
Specialty Stores captured 56.78% of category sales in 2025, while Online Retail Channels are forecast to grow at an 11.95% CAGR through 2031. Specialty retailers remain important where consumers want guidance on fit, capacity, materials, and sport-specific features. This service is particularly relevant for products above USD 100, where customers may want to test comfort and build quality before deciding. Store staff can help compare internal layouts, carrying systems, and the protection offered for different types of equipment. The channel remains useful for families and teams making time-sensitive purchases before a season begins.
Online channels are expanding because they offer broad selections, direct brand assortments, and convenient product comparisons. Digital retail can also support customization, product reviews, and replacement purchases after consumers have used a previous bag. Supermarkets and Hypermarkets address buyers who prioritize accessibility and price comparison, particularly for basic products. Other channels, including factory outlets and club stores, offer further options for value-oriented buyers. Retailers must also consider packaging and material compliance requirements, particularly for products sold in California.
Nota: le quote di tutti i segmenti individuali sono disponibili al momento dell'acquisto del report
Analisi geografica
The United States sports bags market size is anchored by 250 million Americans who participated in at least 1 sport, fitness, or leisure activity in 2025. Texas and Florida support strong demand because of outdoor conditions, large populations, and extensive youth sports systems. Their schools, club programs, and recreation leagues generate institutional purchases and replacement demand. California also carries national importance because its product and packaging policies influence material decisions by suppliers. Manufacturers often prefer common product specifications over state-specific lines, so compliance choices in California can affect products sold across the country.
The Northeast and Pacific Coast metros support premium demand through higher household incomes, dense specialty retail, and participation in fitness and outdoor activities. New York, Boston, Seattle, and San Francisco provide settings where consumers may place greater value on product design and technical features. Florida, Wisconsin, and Arizona have strong golf activity because of their course networks and favorable conditions for play. USGA reported 3.68 million Americans held a Handicap Index in 2025, up 8.20% from the prior year. This provides a defined group of consumers who may need golf-specific bags and related equipment.
The Midwest and South-Central regions remain important for football equipment products. Ohio, Illinois, Pennsylvania, and Michigan each reported more than 240,000 high school sports participants in the 2025-26 school year. School budgets and established football programs can support regular procurement of durable equipment bags. Texas and Florida are likely to retain strong demand as population growth supports new schools and youth programs. The United States sports bags industry therefore has a national base, but its product mix changes with regional sports participation, income levels, and retailer presence.
Panorama competitivo
The United States sports bags market has a low concentration, reflecting a fragmented structure in which no single supplier controls pricing across the category. Nike, Adidas, PUMA, and Under Armour compete across product formats, sports, prices, and sales channels. Their market positions are balanced by specialist brands, private labels, and retailers with their own product assortments. This diversity gives consumers a wide range of price and feature choices. It also means suppliers must compete through material quality, product utility, brand recognition, and distribution access. The United States sports bags market does not show the control by a few players that would characterize a concentrated category.
Under Armour expanded the No Weigh line in 2026 with the No Weigh Lite and No Weigh Playmaker, extending its suspension system into formats aimed at middle-school, high-school, and varsity athletes. Nike introduced its hard-shell suitcase collection in 2026, applying its sports brand to travel products with spinner wheels and removable liners. PUMA also brought compact bag formats into its 2025 PUMA x ROSÉ collection, linking athletic accessories with a limited fashion collaboration. These actions show different routes to demand through performance, travel, and lifestyle use. Retailers also influence competition when they place technical products in prominent stores and online channels. Products with verified material claims can help suppliers stand apart when buyers want clearer sustainability information.
Opportunities remain in sport-specific products for growing activities such as padel, pickleball, and disc golf, which SFIA newly tracked in 2026. These sports can require different storage shapes, protective features, and carrying arrangements. Sustainable premium products are another area where larger brands may use established supply chains and certification processes as an advantage. Smaller companies can respond through narrowly defined product expertise, customization, or local retail relationships. The United States sports bags market will reward companies that make their product benefit clear without losing accessibility for price-sensitive buyers. Counterfeit control and transparent sourcing remain important for protecting trust in branded products.
Leader del settore delle borse sportive negli Stati Uniti
Nike Inc.
Cougar SE
Adidas AG
Selezionare Sport AS
Sotto l'armatura, Inc.
- *Disclaimer: i giocatori principali sono ordinati senza un ordine particolare
Recenti sviluppi del settore
- July 2026: Under Armour expanded its award-winning No Weigh bag collection with 2 new silhouettes, the No Weigh Lite priced at USD 85 and the No Weigh Playmaker. The No Weigh Lite targets middle-school and high-school athletes, while the Playmaker is designed for varsity team transitions.
- March 2026: Sun Mountain Sports collaborated with Victus Sports to introduce a limited-edition golf bag inspired by the iconic yellow Ticonderoga pencil and Victus baseball bat designs. The collection includes the Pencil Bag, priced at USD 350, and the Pencil Bag Jr., priced at USD 300.
- February 2026: Titleist introduced three redesigned golf stand bags: Players S4, Players S4 StaDry, and Players S5. The new models feature redesigned stand systems, improved double-strap systems for weight distribution, durable materials, and enhanced club accessibility.
- December 2025: Under Armour introduced the No Weigh Duffle Backpack, a lightweight and versatile bag designed for athletes and travelers. The product features a convertible carrying system with shoulder and backpack straps, expandable capacity from 41.5 to 51 liters, a dedicated laptop sleeve, organized storage compartments, and weather-resistant UA Storm technology.
Ambito del rapporto sul mercato delle borse sportive negli Stati Uniti
The United States sports bags market report provides a comprehensive analysis of the market, segmented by product type, sports type, and distribution channel. By product type, the market is categorized into backpacks, duffle bags, tote bags, and other bags. Based on sports type, the market covers golf, soccer, baseball, snow and winter sports, football, basketball, and other sports. By distribution channel, the market is segmented into supermarkets and hypermarkets, specialty stores, online retail channels, and other distribution channels. The Market Forecasts are Provided in Terms of Value (USD).
| Zaini |
| Borsoni |
| Tote Bags |
| Altro |
| Golf |
| Calcio |
| Baseball |
| Snow and Winter Sports |
| Calcio |
| Pallacanestro |
| Altri tipi di sport |
| Supermercati / Ipermercati |
| Negozi specializzati |
| Canali di vendita al dettaglio online |
| Altri canali di distribuzione |
| Tipologia di prodotto | Zaini |
| Borsoni | |
| Tote Bags | |
| Altro | |
| Tipo di sport | Golf |
| Calcio | |
| Baseball | |
| Snow and Winter Sports | |
| Calcio | |
| Pallacanestro | |
| Altri tipi di sport | |
| Canali di distribuzione | Supermercati / Ipermercati |
| Negozi specializzati | |
| Canali di vendita al dettaglio online | |
| Altri canali di distribuzione |
Domande chiave a cui si risponde nel rapporto
What is the projected growth rate for United States sports bags through 2031?
The category is projected to grow at a 10.37% CAGR from 2026 to 2031, reaching USD 984.65 million.
Which product type leads sales in United States sports bags?
Duffle Bags lead with 45.36% share in 2025, supported by their use in team equipment transport.
Which sports bag product type is growing fastest?
Backpacks are projected to grow at an 11.68% CAGR through 2031 because they serve school, training, and everyday carrying needs.
Which sales channel is growing fastest for sports bags?
Online Retail Channels are projected to grow at an 11.95% CAGR through 2031, while Specialty Stores lead current sales with 56.78% share.


